Commercial
UAE-India Business Structures: How Entrepreneurs Can Build Cross-Border Operations Without Creating Legal and Tax Risks
Choosing the right UAE-India business structure requires careful planning around tax, ownership, regulation and cross-border payments.
The commercial relationship between the United Arab Emirates and India offers entrepreneurs considerable scope to expand across markets, establish regional headquarters and serve customers through a combination of local and international operations. Yet setting up companies in both jurisdictions is only one part of the exercise. The more difficult task is deciding how those entities should relate to each other, where decisions will be made, how profits will move and which legal obligations will follow the business as it grows.
For an Indian entrepreneur establishing a UAE company, or a UAE-based investor building an Indian operation, the choice of structure can affect tax exposure, access to banking, ownership rights, regulatory approvals and the ability to attract external investment. A structure that works for a closely held trading business may be unsuitable for a technology group seeking venture capital or a family enterprise planning succession.
The starting point should be the commercial purpose of each entity, rather than the jurisdiction in which incorporation appears easiest. A company registration certificate establishes a legal presence; it does not, by itself, determine the tax treatment of income, authorise every proposed activity or resolve the consequences of cross-border transactions.
Choosing Where Each Business Activity Belongs
The UAE and India offer several routes for establishing a business, but the available options serve different purposes. In the UAE, an entrepreneur may consider a mainland company, a free zone entity or, where commercially appropriate, an offshore corporate vehicle. The choice depends on the intended activities, customer base, licensing conditions, ownership requirements and plans for operating within the UAE or internationally.
Mainland companies may suit businesses that need to trade directly across the domestic market, subject to the licensing and ownership rules applicable to the activity. Free zone entities can offer advantages for businesses seeking a specialised commercial environment, international operations or access to particular sector-based infrastructure. However, free zone status should not be treated as a blanket exemption from mainland licensing requirements, customs obligations or federal tax rules.
In India, the structure may involve a private limited company, a limited liability partnership, a branch or another permitted form of establishment. A private limited company is often considered where the business needs a separate operating entity, a formal shareholding framework or the capacity to raise equity. An LLP may suit certain professional and closely held businesses, although its suitability depends on the sector, investor expectations and applicable tax and regulatory treatment.
The two jurisdictions do not need to mirror each other. A UAE holding company may own an Indian operating subsidiary, while an Indian parent may establish a UAE company to manage regional sales, procurement or distribution. In some cases, separate subsidiaries in each country may be more appropriate. The decision should follow the actual division of functions, assets, people and commercial risks, not a preference for a particular corporate label.
Holding Companies And Operating Subsidiaries
One common arrangement is to separate ownership of the business from its day-to-day operations. A holding company owns shares in operating subsidiaries, which conduct activities, employ staff, enter customer contracts and assume operational liabilities in their respective markets. For groups with several business lines or plans for future investment, that separation can improve oversight and make it easier to bring in investors or dispose of a particular division.
A UAE holding company with an Indian subsidiary, for example, may provide a framework for regional investment and group-level governance. The Indian company can maintain its own contracts, accounts, employees and regulatory registrations, while the parent exercises shareholder rights through properly documented corporate decisions. The reverse arrangement may be suitable where the principal business, founders and investment base are in India and the UAE operation serves as a regional extension.
The structure must, however, be supported by more than share certificates and a group organisation chart. Each company should have a defined purpose, adequate records and a clear account of its responsibilities. Directors must observe their duties under the law governing their company, and transactions between related entities should reflect the services, assets or funding actually provided.
Where a parent company routinely directs every operational decision of a subsidiary, the group should examine whether the subsidiary has genuine decision-making capacity and whether its contractual arrangements reflect commercial reality. A separate legal identity remains important, but its practical value can be undermined by poor governance, undocumented intercompany dealings or the commingling of funds.
Tax Residence Is Not Determined By Incorporation Alone
Tax planning is a central consideration in UAE-India structuring, but it should not be confused with selecting the jurisdiction that advertises the lowest headline rate. Both countries apply rules that can bring income within their tax systems, and the treatment of a company may depend on its legal status, activities, management arrangements, income sources and other statutory tests.
The UAE introduced a federal corporate tax regime, with the general rate applying to taxable income above the prescribed threshold. Qualifying free zone persons may obtain a zero per cent rate on qualifying income if they satisfy the relevant conditions; free zone incorporation alone does not secure that treatment. Businesses must examine the rules on qualifying activities and income, substance, transfer pricing, registration, filing and other compliance requirements applicable to their circumstances.
India's tax framework also considers matters beyond the place of incorporation. Its rules on the residence of companies include the concept of place of effective management, subject to the applicable statutory provisions and administrative guidance. Where key commercial and strategic decisions are actually made can become relevant to the tax analysis, particularly when a foreign-incorporated company is managed substantially from India.
A UAE company controlled by founders based in India should not assume that board meetings held in Dubai, or the appointment of UAE-resident directors, will alone settle every residence question. The evidence of how the company operates, where important decisions are taken and how authority is exercised may be material. Equally, an Indian company expanding into the UAE needs to assess whether its activities could create a taxable presence there under the relevant rules.
These issues should be reviewed before operations begin. Retrospective attempts to reconstruct decision-making arrangements can be costly and may not overcome facts that point to a different conclusion.
Cross-Border Payments And The Tax Treatment Of Transactions
Once the corporate structure is established, the movement of money between India and the UAE requires particular attention. Payments may take the form of dividends, interest on shareholder loans, royalties, management fees, technical service charges or payments for goods. Each category can attract different tax consequences, documentation requirements and regulatory restrictions.
The India-UAE double taxation agreement provides a framework for allocating taxing rights and addressing double taxation, but treaty relief is not automatic. The nature of the income, the recipient's entitlement to treaty benefits, beneficial ownership requirements where applicable, and the relevant domestic anti-avoidance provisions all need to be considered. Withholding tax may apply to certain payments leaving India, while the availability of a foreign tax credit depends on the applicable rules and supporting evidence.
Foreign exchange regulation is another important part of the analysis. India's Foreign Exchange Management Act and the rules and regulations made under it govern many cross-border transactions involving Indian residents and non-residents. Overseas investment by Indian residents, including investment in foreign entities, is subject to the applicable overseas investment framework, eligibility conditions, reporting obligations and restrictions. Indian businesses cannot assume that capital can be transferred to a UAE entity simply because the proposed investment has a legitimate commercial purpose.
The legal basis for a payment should be established before the transaction is executed. A shareholder loan, for instance, should have appropriate loan documentation, commercial terms and a repayment framework. Royalty and service arrangements need to identify the relevant intellectual property or services and explain how charges are calculated. Dividends must comply with the corporate law and distribution requirements applicable to the paying company. Proper documentation helps demonstrate the nature of a transaction to banks, auditors and tax authorities, while reducing the risk of payments being challenged or delayed.
Transfer Pricing And The Need For Commercial Substance
Related-party transactions are often unavoidable in a cross-border group, but they require careful treatment. Transfer pricing rules seek to ensure that transactions between associated enterprises are priced in accordance with the arm's-length principle, subject to the legislation applicable in each jurisdiction.
If an Indian subsidiary pays a UAE parent for management services, the group should be able to identify the services provided, explain their commercial benefit and support the fee charged. A management agreement alone may not establish that the services were actually delivered or that the amount charged is reasonable. Similar scrutiny may apply to intercompany loans, intellectual property licensing, distribution arrangements and cost-sharing agreements.
Both India and the UAE have transfer pricing requirements, although their detailed application and compliance thresholds differ. The UAE corporate tax regime includes transfer pricing rules and documentation requirements, while India has its own framework covering international transactions between associated enterprises. Businesses operating across the two countries should assess the obligations separately rather than assume that documentation prepared for one jurisdiction will satisfy the other.
Commercial substance also extends beyond tax compliance. A UAE entity intended to function as a regional headquarters should have a credible business role, suitable personnel or outsourced operational support, appropriate decision-making arrangements and records consistent with its activities. The level of substance required will depend on the entity's functions and the legal provisions relevant to it. Artificial arrangements designed primarily to secure a tax outcome may invite scrutiny without delivering the expected benefits.
Foreign Investment, Ownership And Regulatory Approvals
An entrepreneur establishing a business across the two countries must also consider the rules governing foreign investment. India permits foreign investment under different routes, depending on the sector and the nature of the investment. Some activities are subject to sectoral caps, conditions or government approval, while others may be undertaken under the automatic route, subject to applicable requirements.
The position can become more complicated when an Indian business is funded through a UAE holding company. The investor should establish the ownership chain, identify the ultimate beneficial owners and examine whether any sector-specific restrictions, approval conditions or reporting obligations apply. The source and route of investment may matter as much as the identity of the immediate shareholder.
In the UAE, the appropriate licensing authority, permitted business activities and ownership framework must be checked for the proposed operation. Certain regulated sectors require additional authorisations, and a licence to conduct one activity should not be assumed to cover a different line of business. Banking institutions may also request corporate documents, ownership information, business plans and evidence of the source of funds before opening accounts or processing transactions.
Ownership transparency is increasingly important in both jurisdictions. Companies should maintain accurate shareholder and beneficial ownership information, update statutory records when changes occur and meet the reporting requirements applicable to their legal form. Inconsistent records across jurisdictions can complicate due diligence, delay banking arrangements and create obstacles when investors seek to acquire an interest in the business.
Governance, Succession And Long-Term Planning
Cross-border structures should be designed with future changes in mind. A business that begins with two founders may later admit investors, establish subsidiaries, transfer intellectual property or prepare for a sale. Family-owned enterprises may also need to consider succession, the transfer of shares and continuity of control if a founder dies or becomes unable to manage the business.
Shareholders' agreements, constitutional documents and board procedures should address decision-making authority, reserved matters, dividend policy, restrictions on share transfers, dispute resolution and the circumstances in which an investor may exit. Where founders operate from different countries, the documents should also clarify how decisions are made and how disagreements are handled. Corporate records, contracts and financial reporting should be maintained consistently across the group.
Succession planning deserves particular attention where ownership, assets and family members span more than one jurisdiction. The interaction between inheritance rules, company law, personal status considerations and the location of assets may affect the outcome. A structure that works during a founder's lifetime may not provide the intended result after death unless the relevant legal arrangements have been reviewed in advance.
Dispute resolution should likewise be considered at the outset. Contracts between group companies and external counterparties should identify the governing law and an appropriate forum for resolving disputes. Arbitration may be suitable for some cross-border commercial relationships, but the choice should reflect enforceability, cost, urgency and the nature of the dispute rather than follow a standard clause inserted into every agreement.
Structuring Before Incorporation
The most effective UAE-India business structure is not necessarily the one with the fewest entities or the lowest apparent tax cost. It is the one that aligns ownership, operations, financing and management with the group's commercial objectives while remaining compliant with the laws of both countries.
Before incorporating, entrepreneurs should map the proposed activities in each jurisdiction, identify where contracts will be signed and performed, determine how staff and intellectual property will be allocated, and establish the anticipated movement of capital and profits. Tax advisers, corporate lawyers and foreign exchange specialists can then assess the implications together, rather than address each issue in isolation after the business has begun trading.
The structure should also be reviewed when circumstances change. New investors, acquisitions, changes in management, expansion into regulated activities or a shift in where strategic decisions are taken may alter the legal and tax analysis. Periodic reviews can identify problems before they affect a transaction or attract regulatory attention.
For entrepreneurs building businesses between India and the UAE, incorporation is an administrative milestone, not the end of the structuring process. Long-term value depends on creating a coherent arrangement in which each entity has a clear purpose, cross-border dealings are properly documented and the group can explain how its commercial model operates in practice.
Dr. Sunil Ambalavelil is the Global Executive Chairman of Kaden Boriss, an international law firm specialising in franchise and business agreements. A seasoned legal adviser, he has advised and supported the international growth of numerous global brands, helping them navigate the legal complexities of cross-border expansion.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Dubai Court Rejects Company’s Fresh Bid to Claim Ownership of Luxury Yacht
Court rules that the dispute was conclusively settled by final judgments, ordering the claimant to pay costs and legal fees.
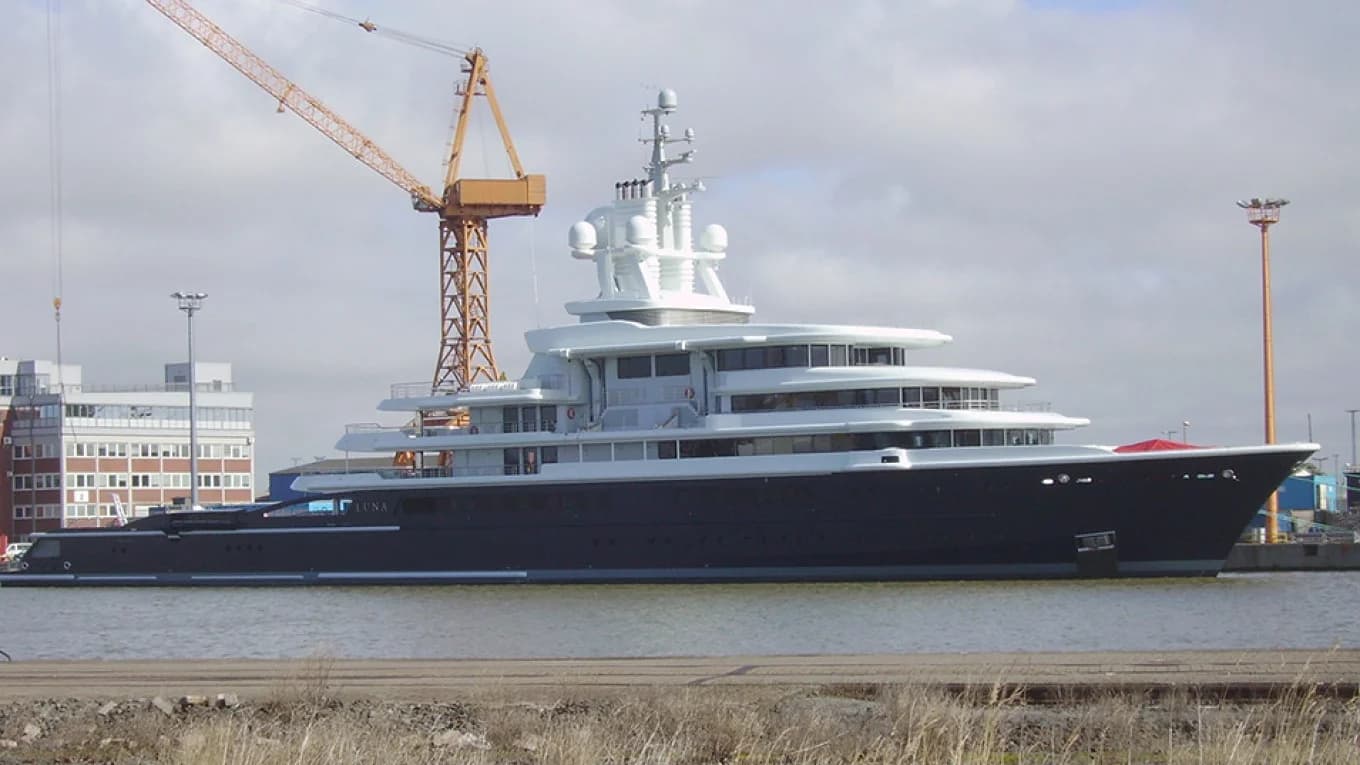
A Dubai court has dismissed a company’s attempt to establish ownership of a luxury yacht, ruling that the matter had already been conclusively determined by final court judgments. The company was ordered to bear the legal costs and pay Dh6,000 in legal fees.
The claimant argued that it had financed the yacht’s construction and was its rightful owner, although the vessel was registered in the name of another company. It also sought to halt enforcement of an earlier judgment, alleging that the ruling had been secured through fraud, deception and collusion.
According to court records, the company said it had entered into agreements with shipbuilders in 2009 to construct the yacht for its benefit. It maintained that the purchase price and associated expenses had been paid from its own funds.
To support its claim, the company submitted payment records, receipts and other documents. It argued that the yacht had subsequently been registered through a separate company established for that purpose and asked the court to recognise its ownership, allowing the vessel to be registered in its name or that of an affiliated entity.
The dispute stemmed from an earlier case in which a court found that the yacht’s registered title was not genuine and recognised another party as its lawful owner. That judgment also invalidated the vessel’s transfer and sale to another entity, permitting the successful party to register it through an affiliated company.
The ruling was subsequently upheld on appeal and by the Court of Cassation, making it final and binding.
Ownership Dispute Cannot Be Reopened
In dismissing the latest claim, the court held that the central question of ownership had already been adjudicated and could not be litigated again. It relied on the legal principle that a final judgment bars a fresh challenge where the parties, subject matter and legal grounds are substantially the same.
The court explained that this principle extends beyond the formal outcome of an earlier case to the essential issues underpinning the judgment. It found that the previous proceedings had definitively addressed the validity of the yacht’s title and ownership, including the invalidity of the registered ownership arrangement.
The claimant could not therefore initiate new proceedings to challenge or circumvent a judgment that had already acquired final legal effect.
The court also considered the corporate structure of the companies involved, emphasising that each registered company possesses a separate legal personality from its shareholders, managers and affiliated entities.
It concluded that the evidence submitted by the claimant was insufficient to establish that it was the yacht’s legal owner or that the company named on the registration documents was merely holding the vessel in name only.
Finding no legal grounds to disturb the earlier judgments, the court dismissed the ownership claim in its entirety. It also rejected the company’s urgent application to suspend enforcement of the previous ruling. The claimant was ordered to pay the court costs and Dh6,000 in legal fees.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Defective Goods After June 1, 2026: UAE Buyers Have Wider Legal Remedies And More Time To Act
New Civil Transactions Law extends remedies for latent defects and gives buyers more time to act.
The UAE Civil Transactions Law, which came into force on June 1, 2026, has made significant amendments to the law relating to defective goods. The changes are of particular relevance to businesses engaged in the sale and purchase of goods, including manufacturers, traders, wholesalers, retailers, distributors, and procurement teams. The new provisions may offer greater flexibility to commercial buyers in the event that a defect is uncovered after the goods have been delivered and put into use.
Where a latent defect is established, the buyer may have several remedies, depending on the circumstances. These can include returning the defective goods, keeping them and seeking the appropriate reduction in the purchase price, or, accepting an equivalent replacement from the seller, who is free from the defect.
The law has extended the period for bringing a latent defect claim from six months to one year from delivery, unless the seller has agreed to a longer warranty period.
The change is particularly relevant to commercial transactions involving machinery, equipment and other goods where the defect may not always be apparent during an initial inspection.
What Counts As A Latent Defect?
A latent defect is typically one that existed prior to delivery, or arose while the goods were with the seller, but could not reasonably have been detected by the buyer, on an ordinary inspection.
The distinction between a latent defect and an obvious defect is therefore important. Where machinery arrives with visible physical damage, for example, the buyer may be expected to notice the problem, and notify the seller at delivery, or within any agreed inspection period.
The position can be different where machinery contains an internal manufacturing defect that becomes apparent only after the equipment has been operated for some time. This may constitute a latent defect if it is established that the defect, or its underlying cause, existed prior to delivery.
In a commercial dispute this question will frequently turn on the evidence. Technical reports, expert inspections, photographs, maintenance records and correspondence between the parties can all be relevant in determining when the defect arose, and whether it could reasonably have been discovered earlier.
Businesses should therefore not always assume that the day on which a problem becomes visible will dictate whether it is regarded as a latent defect.
Remedies Available To The Buyer
The new Civil Transactions Law gives buyers greater flexibility where a latent defect has been established. The buyer may return the defective goods to the seller. Alternatively they may retain them and seek a reduction in the purchase price reflecting the impact or value of the defect. An equivalent replacement may also be provided by the seller, free from the defect.
The availability of a price reduction is particularly relevant in commercial transactions. Returning goods is not always a practical option. Machinery may have been installed and products incorporated into a wider project, with the buyer already incurring substantial costs for transport, commissioning, installation or adaptation. In such cases, keeping the goods while securing the appropriate adjustment to the price can provide a more viable solution than unwinding the transaction.
Replacement can also allow the parties to preserve their commercial relationship without requiring the entire deal to be terminated. The appropriate remedy will, however, depend on the nature of the defect, the goods involved, and the circumstances of the transaction. Businesses should therefore assess the remedies available at an early stage, not assuming that every defect dispute must end in the rejection and return of the goods.
When Does The One-Year Period Begin?
Under the new law, latent defect claims are subject to a one-year period, counted from the day following delivery. This is an extension from the previous six-month period and gives buyers additional time to identify defects that may emerge only after installation, repeated use, or exposure to normal operating conditions.
The longer period should not, however, encourage buyers to delay action. Once a defect is discovered, the buyer should notify the seller promptly and preserve the relevant evidence. It should also exercise caution before carrying out alterations or repairs, that could later make it more difficult to establish the original cause of the problem. Where the defect involves a technical issue, an independent inspection or expert assessment may be appropriate at an early stage. A contemporaneous record of the goods' condition can become very important if the parties dispute, later, whether the defect existed prior to delivery.
The law also allows the parties to agree to a longer warranty period. Businesses should therefore review existing warranty provisions to see whether they offer protection beyond the statutory period.
Inspection And Acceptance Clauses Remain Important
The changes do not detract from the importance of properly drafted inspection and acceptance clauses. A buyer who knew about a defect and accepted the goods will face difficulties in subsequently relying on the same defect. Likewise, where a defect was obvious and could reasonably have been detected during inspection, a failure to raise it within the appropriate period will have an impact on the buyer's position.
This remains particularly significant in B2B contracts. Supply agreements should clearly distinguish between visible defects that must be reported promptly, and latent defects that may emerge only after testing, installation or use. Businesses should also be careful when signing delivery notes, inspection certificates and acceptance documents. A statement that goods have been received "in good condition" may later be relied upon by a seller in a dispute.
For technically complex goods, the contract may need to distinguish between physical delivery and final technical acceptance, following inspection, testing or commissioning. This is particularly important for machinery, industrial equipment, electronics and other products, where a meaningful assessment of performance cannot realistically be completed at the point of delivery.
Suppliers Should Review Their Warranty Clauses
The changes also give suppliers reason to review their standard terms and warranty provisions. A contractual warranty stating that liability ends after six months may not, in itself, fully address the buyer's statutory rights under the new regime governing latent defects.
Suppliers should therefore ensure that their contracts are consistent with the new law, and establish a clear procedure for dealing with reported defects. This should include the applicable warranty period, inspection requirements, notification process, repair or replacement arrangements, and responsibility for transportation, inspection and testing costs.
The contracts should also make clear how disputes over the cause of a defect should be investigated and resolved. This can be particularly important where the parties disagree over whether the problem arose before or after delivery.
Manufacturers and distributors may also need to examine the relationship between a manufacturer's warranty and the liabilities of the local seller. Without appropriate contractual protection, a UAE seller may find themselves liable to the buyer, with limited recourse against the manufacturer or up-stream supplier.
Practical Impact For UAE Businesses
The new law provides buyers with a broader framework for handling defective goods, particularly where a problem is not immediately apparent. The outcome of a latent defect dispute will nevertheless continue to depend largely on the terms of the contract, and the evidence available to establish the nature and timing of the defect.
Buyers should document problems carefully and notify sellers promptly, even if the one-year statutory period has not expired. Suppliers, meanwhile, should review their standard sales terms, warranty periods and acceptance procedures, to ensure they are in line with the new legal framework. For both sides, properly drafted contracts are fundamental to managing the risk.
The new regime does not eliminate the need for clear inspection, notification and warranty provisions. It makes it increasingly important for businesses to ensure that these provisions work consistently with the statutory rights and remedies available under UAE law.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Saudi Research Centre Publishes Detailed Commentary On Civil Transactions Law
Commentary explains the law’s provisions, scope and links to related legislation for judges, lawyers and researchers.
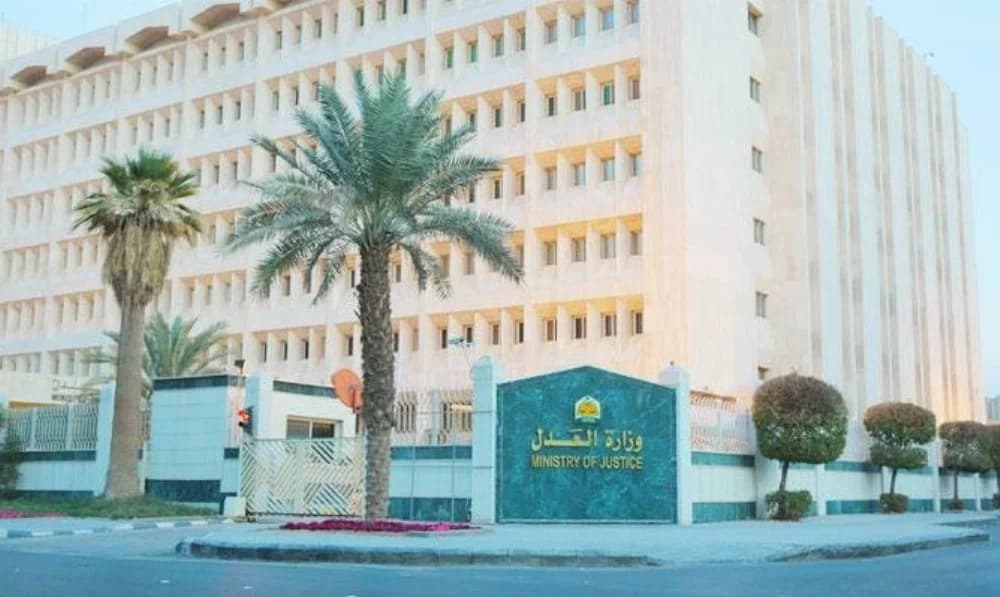
The Research Centre at Saudi Arabia’s Ministry of Justice has published a four-part detailed commentary on the Civil Transactions Law following its approval by Minister of Justice Walid Al-Samaani.
The commentary examines the provisions of the law in detail, explaining the intended meaning of each article and the legal terminology used. It also sets out the conditions governing the application of each provision and the legal effects arising from it, supported by practical examples and distinctions between cases falling within a specific provision and those outside its scope.
The publication also examines the relationship between the provisions of the Civil Transactions Law and other relevant legislation. It explains the legal consequences of failing to comply with its provisions and identifies rules considered matters of public policy that cannot be altered by agreement between the parties.
The commentary is intended to serve judges, lawyers, academics, researchers, legal advisers and law students by providing a detailed reference for understanding and applying the law.
The publication is the third in the Research Centre’s legal commentary series, following earlier commentaries on the Law of Evidence and the Personal Status Law.
The first part covers the introductory chapter and sources of obligations, while the second examines provisions governing obligations. The third part focuses on nominate contracts, and the fourth addresses real rights and the law’s final provisions.
The commentary is intended to deepen understanding of the Civil Transactions Law and provide greater clarity on its provisions. The Ministry said the publication would help promote their proper application to different factual circumstances, strengthen legal certainty and support the quality of judicial decisions, while contributing specialised legal knowledge to the wider legal community.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Kaden Boriss Wins Global Chambers Law Firm Of The Year Award
Dubai-based law firm recognised at BGLS IP & Litigation Summit for its cross-border practice and global legal alliances.
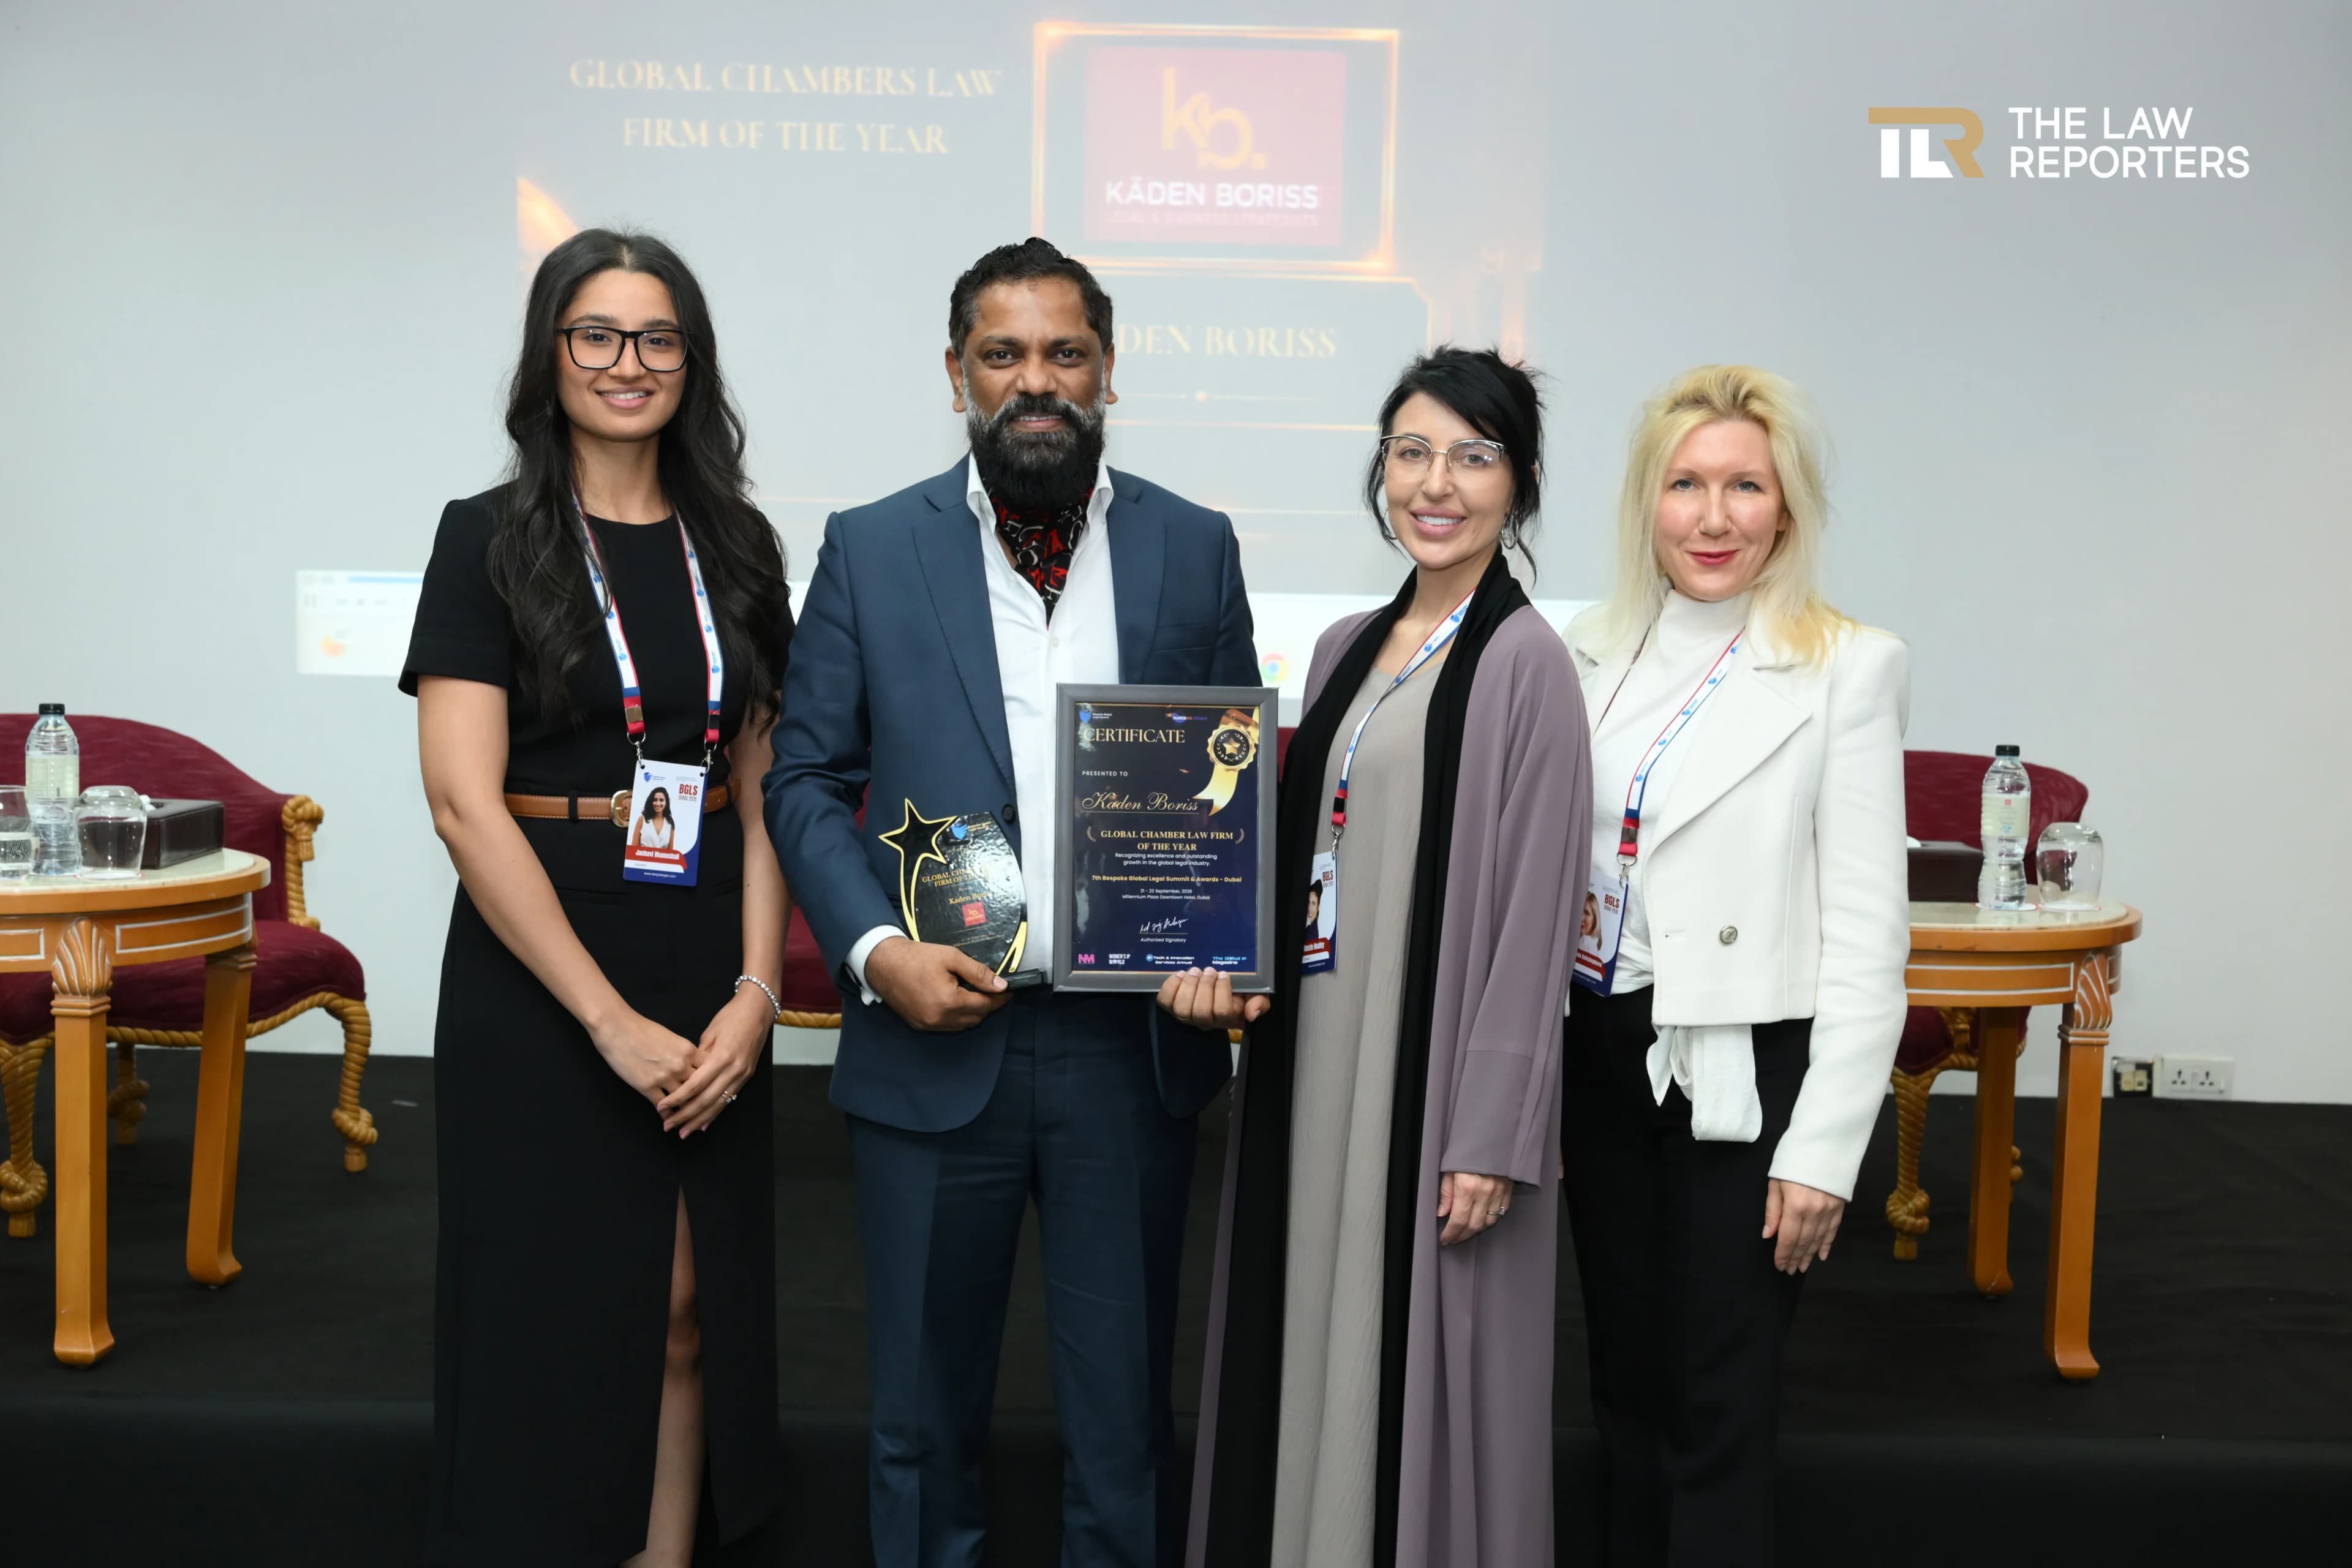
Dubai-based leading international law firm Kaden Boriss has been awarded with ‘Global Chambers Law Firm of the Year’ at the seventh Bespoke Global Legal (BGLS) IP & Litigation Summit for its cross-border legal practice and international alliances.
Dr Sunil Ambalavelil, Global Executive Chairman of Kaden Boriss, received the award on behalf of the firm during the two-day summit, which took place on September 21 and 22 at the Millennium Plaza Downtown Hotel in Dubai.
The BGLS Summit, which convened under the theme ‘Innovation Meets Governance: Charting the Future of IP, AI & Dispute Resolution’, attracted more than 300 legal, corporate and technology professionals who gathered to discuss the changing legal landscape driven by artificial intelligence, intellectual property, digital technology and increasingly complex cross-border disputes.
The summit saw a packed agenda covering AI and IP ownership, machine-generated works, litigation funding, legal technology in dispute resolution, digital assets, regulatory compliance and the use of AI in arbitration and construction claims. Keynote speakers represented organisations such as International Trademark Association, Airbus, Baker & McKenzie Wong & Leow, Deloitte and GE Vernova.
The summit explored the challenges facing law firms and corporate legal departments as technology transforms the dispute management and legal services landscape. With sessions covering AI training and workforce development, technology-enabled legal operations and the need for legal teams to evolve to meet emerging regulatory and commercial risks.
The BGLS Summit brought together legal practitioners, corporate counsel, technology specialists and business leaders to discuss the latest developments affecting intellectual property, litigation and dispute resolution. The award was presented during the first day of the conference as part of the summit’s programme of professional recognition and networking.
Dr Sunil Ambalavelil said that the award was a recognition of the firm’s approach to combining legal expertise with international collaboration.
“This award is a recognition of the work our teams and alliance partners have been doing across jurisdictions. Cross-border matters increasingly require lawyers to understand not only the law, but also the commercial and regulatory environment in which clients operate. Our focus is on providing coordinated, practical advice while maintaining the professional standards and confidentiality expected in complex international matters,” he said.
Based in Dubai, Kaden Boriss advises a broad range of organisations from startups, multinational enterprises to family-owned businesses and high-net-worth individuals. Its practice areas cover dispute resolution, arbitration, mergers and acquisitions, insolvency, construction, real estate, maritime, aviation, intellectual property and family office advisory.
The firm’s cross-border practice covers both inbound investment into the UAE and expansion by UAE-based businesses into international markets, working with alliance partners across the Gulf region, the UK, Europe and Asia. It can also advise clients looking to enter the US market, with company formation and related visa coordination.
The firm said its international network means it can manage multi-jurisdictional matters through a single point of contact, while engaging local counsel and regulatory specialists where formal representation or jurisdiction-specific expertise is required.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Unpaid School Fees: Abu Dhabi Court Orders Parent To Pay Dh197,680
Woman held jointly liable for Dh142,800 after cheque drawn on her account could not be cashed.
The Abu Dhabi Commercial Court of First Instance has ordered a parent to pay Dh197,680 to a private school for unpaid tuition fees relating to the enrolment of his children.
The court also held a woman jointly liable for Dh142,800, the value of a cheque issued from her bank account to the school. The cheque could not be cashed because it had been prepared in a manner that prevented payment. The two were also ordered to jointly pay Dh3,000 in compensation.
According to court records, the parent had enrolled his children at the private school but failed to settle the tuition fees. He later handed the school a cheque towards part of the outstanding amount. Although the cheque was drawn on the woman's account, the school was unable to cash it.
The published ruling referred to an earlier criminal case connected with the cheque but did not disclose the penalty imposed in that case. It also did not explain the nature of the woman's relationship with the parent.
School’s Claim
The school brought a civil case seeking Dh197,680 from the parent for the unpaid fees. It also asked the court to hold the woman jointly responsible for Dh142,800, representing the value of the cheque, and sought Dh15,000 in damages.
The school submitted invoices and account statements showing the outstanding tuition fees, a copy of the cheque, evidence that it had been returned unpaid and a copy of the related criminal judgment.
The woman asked the court to dismiss the claim against her, arguing that she was not involved in the underlying dispute. The court rejected her argument, noting that the cheque had been issued from her account in favour of the school.
The court also found that she had not produced evidence showing that the amount covered by the cheque had been paid or that she was no longer liable for it.
The parent appeared before the court but was unable to successfully challenge the school's evidence. He also failed to establish that the outstanding tuition fees had already been paid.
Court’s Decision
The court ordered the parent to pay Dh197,680 to the school. The woman was held jointly responsible with him for Dh142,800, corresponding to the value of the unpaid cheque.
The two were also ordered to jointly pay Dh3,000 in compensation, in addition to court expenses and Dh200 in legal fees. The court rejected the school's remaining claims.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels
President Trump’s White House Media Ban: A Court Rebuke That Leaves The Press Fight Unresolved
A court victory for the press, but the wider battle over White House media access is now moving into the courts.
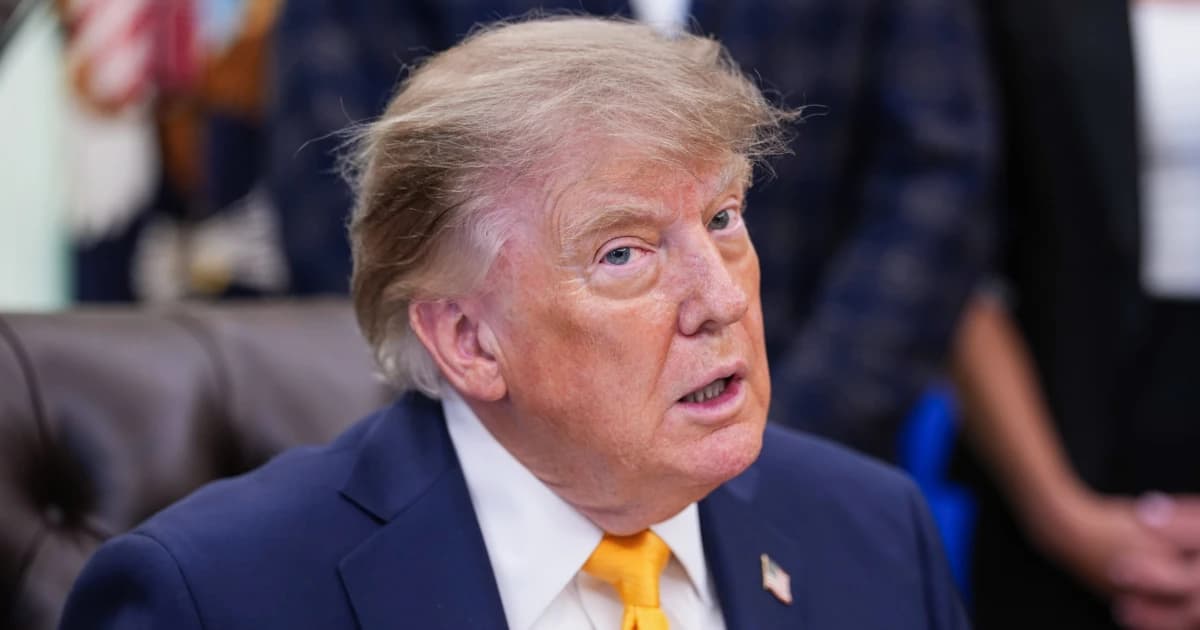
The confrontation between Donald Trump and the American news media has entered a new and potentially consequential phase. A federal judge has ordered the White House to restore access to journalists from CNN, MS NOW and Politico after the Trump administration barred the three organisations from the White House grounds.
US District Judge Timothy Kelly’s ruling does not finally settle the constitutional dispute. Instead, it imposes a 14-day temporary restraining order while the broader case proceeds. Nevertheless, the decision is significant because the judge concluded that the news organisations were likely to succeed in demonstrating that their press credentials had been revoked without constitutionally adequate due process.
The immediate chronology is revealing. Trump announced the ban on September 18, accusing the three outlets of publishing what he described as false and negative reporting. The administration subsequently sought to justify the action in court partly on national-security grounds. The three organisations responded with a lawsuit alleging violations of their First and Fifth Amendment rights.
Kelly was particularly sceptical of the government's explanation. His ruling said there was little factual support for the proposition that removing the outlets' hard passes would protect national security. He also pointed to the president's own public explanation for the ban, which centred on the outlets' alleged reporting failures rather than a clearly identified security threat.
That distinction matters. Governments can legitimately impose restrictions on access to sensitive facilities, but the constitutional question becomes considerably more difficult when access appears to be withdrawn because officials object to the content or perceived tone of journalism. The case therefore raises an issue broader than the three organisations involved: can a president use control over access to the White House to punish news organisations for unfavourable coverage?
Due Process Is At The Centre Of The Case
One of the most important aspects of Kelly's ruling is that it rests, at this stage, principally on due process, rather than providing a final ruling on the First Amendment claims.
The judge relied on existing precedents from the US Court of Appeals for the District of Columbia Circuit concerning White House press access. Those precedents indicate that journalists cannot simply have protected access removed without appropriate notice and an opportunity to contest the decision. Kelly concluded that the process followed by the administration did not appear to meet that standard.
The Justice Department, by contrast, argued that access to the White House is a privilege rather than an entitlement and maintained that the president possesses substantial authority to determine which organisations receive access. Government lawyers also sought to link the outlets' reporting to national-security concerns and questions of professionalism and decorum.
The competing arguments therefore involve two different conceptions of presidential power. The administration's position emphasises executive control over access to the White House. The news organisations' position emphasises constitutional protections and the danger of allowing access decisions to become a mechanism for retaliating against journalism.
The eventual resolution of that conflict could have implications well beyond CNN, MS NOW and Politico.
The Extraordinary Moment After The Ruling
The significance of the dispute became even clearer on Thursday. Kelly's order was issued overnight, requiring the administration to "immediately" restore the journalists' credentials. Yet reporters from the three organisations were initially turned away from the White House grounds the following morning. The organisations subsequently sought an emergency hearing, arguing that officials were continuing to prevent journalists from exercising the access the court had ordered restored.
The White House subsequently said that the restoration process had begun early that morning and that the affected journalists' credentials had been reactivated. The reporters were eventually allowed back into the complex around midday.
That episode is important analytically because it demonstrates that the dispute is no longer simply about whether Trump can impose a ban. It is also about how presidential agencies implement judicial decisions concerning access to the presidency itself.
For the moment, the immediate confrontation has been defused. But the fact that journalists were initially prevented from entering despite the court's order illustrates how quickly a dispute over constitutional principles can become an operational confrontation between the executive branch and the judiciary.
The Press Pool Adds Another Layer
The controversy has also exposed the importance of the White House press pool. A rotating group of major television networks normally shares the responsibility of covering presidential movements and distributing video and other material to the wider media. After CNN was excluded, the other major television networks suspended much of their pool coverage in solidarity.
This had practical consequences. Without the normal independent television pool, audiences were increasingly dependent on material supplied directly by the White House. During President Trump's meeting with Chinese President Xi Jinping, for example, major US television networks were present but were not providing their usual pool coverage.
The issue is therefore not simply whether three reporters can enter a building. The press pool exists partly because presidential events cannot be independently covered by every organisation at every location. One outlet's exclusion can affect the wider information ecosystem.
The latest reporting indicates that the three organisations have regained physical access, but questions surrounding CNN's participation in the television pool have remained unresolved.
A Constitutional Dispute With A Wider History
The current case also fits into a longer pattern of conflict between Trump's administration and sections of the American press.
The White House has previously attempted to restrict access for journalists and news organisations with which it has had contentious relationships. Courts have previously intervened in disputes involving White House press credentials, including an earlier case involving CNN journalist Jim Acosta. Kelly himself was the judge who ordered CNN's access restored in 2018.
What makes the present case especially significant is the scale of the action. The administration did not merely remove an individual correspondent; it targeted three established news organisations.
Trump has also suggested that additional outlets could face similar treatment. When viewed alongside the administration's argument that White House access is a presidential privilege, the case raises a broader question about whether the executive branch can determine which news organisations are sufficiently acceptable to receive routine physical access.
That is precisely why the eventual judicial reasoning may matter more than the immediate 14-day order.
What Happens Next?
The temporary restraining order is not a final judgement. The three organisations are expected to seek longer-term protection while the underlying constitutional case continues. Judge Kelly has set September 28 as a deadline for the plaintiffs' request for a preliminary injunction and indicated that he intends to act expeditiously.
The administration has indicated that it wants to challenge existing precedent governing White House press access. The Justice Department has argued that earlier decisions protecting journalists' access should be reconsidered.
Consequently, the next stage could involve a more fundamental examination of the relationship between presidential authority, press access and the First and Fifth Amendments.
The immediate legal victory for the three outlets should therefore not be confused with a final resolution. Kelly's order primarily establishes temporary protection and addresses the apparent lack of adequate process. The substantive First Amendment questions remain to be litigated.
The Larger Democratic Question
At its core, the dispute is about more than Trump and three media organisations. It concerns the institutional relationship between a powerful executive and a press corps whose job includes scrutinising that executive.
Presidents inevitably have legitimate interests in security, order and the management of restricted government facilities. Journalists, meanwhile, have legitimate interests in maintaining access necessary to report on the president and government.
The difficult constitutional question arises when those two interests collide and the government's justification for restricting access overlaps with dissatisfaction over the substance of news coverage.
That is why Kelly's rejection of the administration's national-security rationale is particularly consequential. He did not merely accept the government's assertion that security was at stake; he examined the evidentiary record and found it insufficient at this preliminary stage.
The next stages of the litigation will determine whether that reasoning survives more extensive judicial scrutiny and whether the court ultimately reaches the First Amendment questions raised by the three organisations.
For now, CNN, MS NOW and Politico are back inside the White House. But the underlying confrontation remains. The 14-day order has restored access; it has not resolved the argument over who ultimately controls the boundaries of presidential press access — or how far that power can extend when the journalism in question is politically inconvenient to the president.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Directors And Bankruptcy In The UAE: When Can Management Face Personal Legal Exposure?
UAE bankruptcy law can expose directors, managers and those exercising actual control to personal liability for misconduct.
The separate legal personality of a company is a cornerstone of UAE commercial law, but it has never been an impenetrable shield. When a company slides into insolvency, the conduct of its directors and managers comes under intense judicial scrutiny, and the corporate veil can be lifted with serious personal consequences.
This area is now governed by Federal Decree-Law No. 51 of 2023 on Financial Restructuring and Bankruptcy (the "Bankruptcy Law"), which came into force on May 1, 2024, repealing the previous regime under Federal Decree-Law No. 9 of 2016. Its implementing regulation was issued through Cabinet Resolution No. 94 of 2024 and, since July 15, 2025, a dedicated Bankruptcy Court, headquartered in Abu Dhabi, has heard bankruptcy cases.
Critically, the new law widens the potential scope of liability beyond board members and managers to any person responsible for the actual management of the company, effectively capturing shadow and de facto directors, as well as those responsible for liquidation. This article examines the principal grounds of personal exposure, leading case law and practical lessons for management.
Decisions Made During Financial Distress
The moment a company approaches the zone of insolvency, the risk calculus for its management changes fundamentally. A debtor must apply for the opening of proceedings within 60 days of ceasing payments or becoming aware that it cannot meet its debts.
However, late filing no longer triggers automatic criminal liability under the new law, with the focus having shifted towards the substance of the company's solvency and the conduct of those managing it. More significantly, Article 246 of the Bankruptcy Law imposes liability on directors, managers and any person responsible for the actual management of the company where that person takes undue risks in relation to the company's affairs during the two-year period preceding insolvency.
Where liability is established, the court can order that person to pay an amount sufficient to restore the company's position as if the wrongful act had not occurred. Reckless trading, speculative ventures and continuing to incur credit with no realistic prospect of repayment during financial distress can therefore create significant grounds for personal claims.
Improper Disposal Of Company Assets
Asset-stripping during the period immediately preceding bankruptcy is a classic trigger of liability. Disposing of company assets at an undervalue within the two years preceding insolvency is expressly among the acts for which management can be held personally accountable under Article 246. Sales of property, transfers to related parties or gratuitous dispositions made when the company was already unable to pay its debts may be unwound, with the responsible individuals potentially ordered to make good the resulting shortfall.
Liability may also attach where mismanagement causes the company's assets to fall below 20 per cent of its due debts during the two years before payments ceased, an insufficiency threshold that has its roots in the earlier legal regime.
Preferential Treatment Of Certain Creditors
Equality of treatment among creditors, reflected in the principle of pari passu distribution, is a fundamental feature of insolvency proceedings. Entering into a preference transaction with a creditor during the two-year suspect period preceding insolvency can expose the individuals responsible to a personal contribution order. Paying a favoured supplier, a related company or a personally guaranteed debt ahead of the general body of creditors, particularly when the company is insolvent, is precisely the type of conduct that the courts may scrutinise, reverse and penalise.
Corporate Records And Financial Reporting
Proper books and records are among a director's first lines of defence. Failure to maintain adequate accounting records, or their concealment, falsification or destruction, deprives the trustee and the court of the ability to reconstruct the company's affairs and may therefore be treated with particular severity.
Under the framework as developed following early case law, misfeasance relating to company books, disposal of assets or preferential payments can form the basis of management liability, introducing an element of culpable conduct rather than mere insolvency. Separately, Article 162 of the Commercial Companies Law, Federal Decree-Law No. 32 of 2021, provides an independent basis for claims against directors in cases involving fraud, abuse of authority or gross mismanagement.
Consequences Of Fraudulent Conduct
Where dishonesty is involved, exposure can escalate from civil compensation to criminal sanctions. Civil liability is primarily restorative, requiring compensation proportionate to the individual's fault, whereas criminal liability under the Bankruptcy Law's penal provisions is punitive and can result in imprisonment and fines. Fraudulent bankruptcy offences typically involve concealing or destroying books, fabricating losses, hiding assets or acknowledging fictitious debts. Procedurally, the courts also have coercive powers. The Bankruptcy Court may impose travel bans on directors and board members as precautionary measures during proceedings, while asset freezes affecting personal wealth may also be ordered where legally justified.
Case Law
Marka Holdings PJSC (Dubai Court of First Instance, October 10, 2021). In what was reported as the first known instance of such an order in the UAE, the Dubai Court of First Instance held the directors and managers of the insolvent listed company personally liable for outstanding debts exceeding Dh448 million. The decision was based on findings that the company's assets could not cover at least 20 per cent of its debts, together with findings of management misconduct. The court also stripped the directors and managers of their management rights, imposed freezing orders over their personal assets and referred the matter to the Public Prosecutor. The decision attracted significant attention and was followed by a legislative amendment requiring, in addition to the 20 per cent shortfall, proof of culpable acts concerning company books, asset disposals or preferential payments.
Dubai Court of Cassation, November 2024. The Court of Cassation held former shareholders personally liable as de facto managers for Dh850 million, finding that, despite having formally exited management more than 10 years earlier, they had retained real influence over the company's decisions. The judgment was reported as the largest personal liability award of its kind in UAE history.
Conclusion
The UAE has moved towards a modern, accountability-driven insolvency regime in which the protections of separate legal personality and limited liability do not extend to misconduct. Federal Decree-Law No. 51 of 2023, together with the developing case law, makes clear that directors, managers and anyone exercising actual control over a distressed company must carefully consider their conduct as insolvency approaches.
Management should act early, obtain professional advice, preserve company assets, treat creditors fairly, maintain accurate records and document the commercial rationale behind significant decisions. In the two years preceding insolvency, transactions and management decisions may later be examined by a trustee and a specialised court. Where misconduct is established, the financial consequences may extend beyond the company to the individuals responsible.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Changing a UAE Company's Licensed Activity: What Businesses Need to Consider Before Making the Change
Businesses changing their activities must assess approvals, corporate records and the appropriate licensing structure.
A company's business activities may evolve as its operations, commercial objectives and market focus change. Where a UAE company intends to undertake an activity that is not covered by its existing licence, it should first assess the applicable licensing requirements and obtain the necessary approvals before commencing the new activity. The process will depend on the company's licensing jurisdiction, the nature of the proposed activity and whether additional regulatory approvals are required. Businesses should also consider whether the change requires amendments to their corporate records or whether a separate entity or licensing structure may be more appropriate.
Identifying The Appropriate Business Activity
A business activity is a fundamental part of a company's licensing framework in the UAE. The Ministry of Economy and Tourism states that there are more than 2,000 economic activities available for licensing, with the activity determining the type of licence required. Businesses should therefore identify the specific economic activity that corresponds to their proposed operations rather than relying only on a general description of the intended business.
This is particularly relevant where a company is expanding its services or entering a new sector. An activity that appears commercially similar to an existing activity may nevertheless have different licensing requirements. Before applying for an amendment, the company should establish how the proposed operations are classified by the relevant licensing authority and whether the activity can be added to the existing licence.
The applicable authority will depend on where the company is established. For mainland companies, licensing is handled by the relevant economic department or other competent authority in the emirate. Free zone companies are subject to the licensing requirements of the relevant free zone authority. The UAE's official business guidance directs businesses to the relevant emirate-level authority for information on incorporation and licensing requirements.
The company should also determine whether the proposed activity can be added to its existing licence. Depending on the rules, the amendment may involve adding or removing an activity or making corresponding changes to registered information.
Mainland And Free Zone Considerations
The procedure for changing a business activity is not uniform across the UAE. Each licensing authority has its own procedures and requirements, and the activities available for licensing may differ between jurisdictions. Businesses should therefore rely on the rules and processes of the authority that issued, or will amend, the relevant licence.
For mainland companies, the business should check the requirements of the relevant emirate's licensing authority. The Ministry of Economy and Tourism identifies the departments of economic development and other competent authorities as the bodies through which mainland businesses complete licensing procedures. Process, documents and approvals can vary depending on the emirate and activity.
For free zone companies, the proposed activity must be assessed against the activities permitted by the relevant free zone. The company should also confirm whether the activity can be carried out under its existing licence category and whether the free zone requires additional documentation or approvals.
The distinction between the company's existing activity and the proposed activity is therefore important. A company should not assume that an existing licence automatically covers a new service simply because the activities are commercially related.
The company's legal form may also need to be considered. Depending on the proposed activity and the requirements of the relevant authority, an amendment to the existing structure may be possible, while in other circumstances a different licensing arrangement may be considered.
Additional Regulatory Approvals
Certain activities are subject to regulation beyond the ordinary licensing process. In such cases, obtaining an amendment to the commercial licence may not be the only requirement before the company can commence the proposed activity.
The Ministry of Economy and Tourism identifies various activities that require additional approvals from the relevant government authorities. For example, legal activities and legal consultancy require approval from the Ministry of Justice, while telecommunications activities are subject to approval from the Telecommunications and Digital Government Regulatory Authority. Other sectors, including certain transport, health, tourism and financial activities, may also require additional regulatory approvals.
Businesses should therefore establish whether the proposed activity falls within a regulated sector before submitting an application to amend their licence. The relevant authority may require an approval, permit or no-objection from the regulator responsible for that activity.
Activities with a strategic impact are subject to a separate regime. Under Cabinet Resolution No. 55 of 2021, a list of activities is designated as having a strategic impact and is subject to specific licensing controls. The Ministry of Economy and Tourism states that foreign participation in these activities may be subject to ownership percentages and other conditions determined by the relevant regulatory authority.
The additional approval process will depend on the particular activity. A company should therefore assess these requirements at the planning stage rather than commencing the new activity and addressing the regulatory position afterwards.
Corporate And Compliance Considerations
Changing a licensed activity can have implications beyond the trade licence itself. Businesses should review whether the proposed change requires corresponding amendments to their corporate documents or registered information.
The UAE Commercial Register framework, under Federal Decree-Law No. 37 of 2021, provides for commercial and economic registers covering traders and licensed economic activities, including updates and changes to registered information. Businesses should therefore consider whether a change to the licensed activity must also be reflected in the relevant registers.
The company's existing constitutional documents should also be reviewed where appropriate. Depending on the company's legal form and the nature of the proposed change, amendments to the company's Memorandum of Association or other corporate documents may be required.
Businesses should also ensure that their actual operations remain consistent with their licensed activities. Under Article 11 of the Commercial Companies Law, a company must obtain all the approvals and licences required to engage in its business activities before commencing business practice. This requirement is set out in Federal Decree-Law No. 32 of 2021 on Commercial Companies, which was amended by Federal Decree-Law No. 20 of 2025.
The position for free zone companies should be considered separately because their governing framework may differ. Official UAE guidance states that free zone businesses are governed by the relevant free zone authority and, generally, that the Commercial Companies Law does not apply where the free zone has its own special framework.
This makes the timing of the amendment important. A company should not treat the filing of an application to change its activity as equivalent to obtaining the required authorisation. The company should confirm that the relevant amendment and any additional regulatory approvals have been completed before commencing the new activity.
Changing An Activity Or Establishing A New Entity?
For some businesses, the question may not be limited to whether an activity can be added to an existing licence. It may also be necessary to consider whether the proposed business should operate through the existing company or through a separate entity.
There is no single approach that applies to every business. The appropriate structure will depend on factors including the proposed activity, the company's existing legal form, the licensing jurisdiction and any regulatory requirements applicable to the new business.
Where the proposed activity is substantially different, the relevant authority's requirements should be reviewed before deciding how to proceed. A separate entity may also need to be considered where the proposed activity cannot be accommodated under the existing licensing structure.
Businesses should therefore assess the regulatory position before making structural decisions. Confirming the correct activity classification, the availability of the activity under the relevant licence and any additional approval requirements can help determine whether an amendment to the existing company or a separate licensing structure is appropriate.
Changing a business activity in the UAE should be approached primarily as a licensing and compliance matter, rather than simply an administrative amendment. By identifying the correct activity, confirming the requirements of the relevant licensing authority and addressing any additional regulatory approvals, businesses can ensure that their licensed activities remain aligned with their actual operations.
Anushka Rastogi is a Legal Associate at UAE-based legal consultancy Kaden Boriss.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Misdemeanor Court Acquits Manager In Dhs6.3 Million Embezzlement Case
Court finds no conclusive evidence of embezzlement or criminal intent and rejects the related civil claim.
The Misdemeanor Court in Dubai has acquitted a company manager accused of embezzling Dh6.23 million from company funds, ruling that the evidence did not establish either the alleged misappropriation or an intention to unlawfully take the money.
The court also rejected a civil claim filed against the manager, ordering the complainants to bear the costs and legal fees.
The case arose after two partners in the company accused the manager, who was responsible for its management and financial affairs, of taking company funds through withdrawals and other financial transactions between 2018 and 2024. The partners also sought temporary civil compensation of Dh51,000.
Court Examines Company Accounts
During the proceedings, the court appointed an accounting expert to examine the company's financial records, accounts and supporting documents. The expert found that the transactions under scrutiny had been recorded in the company's books and in the relevant partner's current account.
The examination also found that payments relating to profit distributions were based on decisions signed by the complainants or their authorised representatives. The court considered this significant because it indicated that the complainants were aware of and had approved the transactions in question.
The court further noted that the withdrawals and other financial transactions had been reflected in the company's accounts, while the profit distribution decisions carried the signatures of the complainants or their representatives.
Evidence Insufficient To Prove Embezzlement
In its judgment, the court held that a breach-of-trust offence requires proof that money was entrusted to the accused under one of the contractual arrangements recognised by law, followed by an intention to misappropriate or use the money in a manner that causes harm to its owner.
The court found that the evidence presented by the complainants, including their statements and the accounting report submitted during the proceedings, was insufficient to establish the alleged offence. The findings of the court-appointed expert did not support the claim that embezzlement had occurred.
It also found that the documents before it did not provide conclusive evidence of an intention by the manager to unlawfully take the funds. The existence of debit balances or financial and accounting disputes between business partners, the court said, was not by itself sufficient to establish criminal intent.
Court Rejects Civil Claim
Based on its assessment of the evidence, the court concluded that the legal elements required to establish a breach of trust had not been established against the manager.
The court therefore acquitted the manager, rejected the related civil lawsuit and ordered the complainants to pay the costs and legal fees.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.