For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Finance
The Money Mule Trap: How UAE Bank Account Holders Can Become Entangled in Financial Crime
UAE money mules face imprisonment and heavy fines for handling illicit funds through personal and corporate accounts.
An invitation to receive money into a bank account and transfer it elsewhere may sound like an easy way to earn additional income. It could be presented as a part-time job, an administrative task or a service for which the account holder receives a commission. In reality, such arrangements can form part of a money laundering operation, placing individuals who agree to participate at risk of criminal investigation in the UAE.
A person who allows their bank account to be used to receive and move funds on behalf of others is commonly described as a money mule. Criminal networks use these intermediaries to distance themselves from the proceeds of fraud and other offences. By moving money through several accounts, they attempt to disguise its origin and make it harder for banks and investigators to identify the ultimate beneficiaries.
The methods vary. Some individuals are asked to rent out their accounts or hand over banking credentials, while others receive transfers from unfamiliar people and forward the money to designated beneficiaries. More elaborate arrangements involve setting up companies, issuing invoices for services never provided or converting cryptocurrency into cash.
Although some participants knowingly assist criminal networks, others may be drawn in through misleading employment advertisements, social media approaches or promises of legitimate commissions. Their knowledge and conduct, however, remain central to determining whether criminal liability arises.
How Money Mule Arrangements Operate
Money mule schemes rely on the use of accounts belonging to people who are not directly involved in the original criminal activity. Funds obtained through fraud or other unlawful conduct may first enter a personal account before being transferred to several other accounts. Each additional transaction can make the movement of the money more difficult to trace.
Recruitment often takes place online. An individual may be told that a company needs someone to receive customer payments, process transactions or manage transfers because of restrictions on its own banking arrangements. The person is promised a fixed payment or a percentage of the money handled.
Other schemes involve opening bank accounts or registering companies for third parties. Participants may be instructed to share debit cards, passwords or one-time passwords, or to use their accounts to receive payments from people they have never dealt with.
The use of corporate accounts can make these arrangements appear more credible. Payments may be described as consultancy fees, marketing expenses or purchases of equipment, even where no goods have been delivered or services performed. Such transactions can create a false appearance of ordinary business activity.
An account holder who accepts these instructions may become involved in the movement of criminal proceeds, even if they did not participate in the offence that generated the money.
The UAE's Legal Framework
The principal legislation governing money laundering in the UAE is Federal Decree-Law No. 10 of 2025 Regarding Anti-Money Laundering, and Combating the Financing of Terrorism and Proliferation Financing. The law replaced Federal Decree-Law No. 20 of 2018 and came into force on October 14, 2025.
Article 2 defines the conduct that may constitute money laundering. It applies where a person knows, or where sufficient indications or evidence exist to believe, that funds represent proceeds of a predicate offence and intentionally converts, transfers or carries out transactions involving those proceeds for the purpose of concealing or disguising their illicit origin.
The provision also covers concealing the true nature, source, location, movement or ownership of criminal proceeds, as well as acquiring, possessing or using them. Assisting the perpetrator of the underlying offence to evade punishment is also included.
Money laundering is treated as a separate criminal offence. A conviction for the original crime is not necessary to establish the illegal origin of the proceeds. Knowledge may be inferred from the circumstances surrounding the transactions, rather than being determined solely by what an individual claims to have known.
This distinction is important in money mule cases. Someone who did not organise a fraud may still face investigation for handling or transferring its proceeds. However, the mere receipt of suspicious funds does not automatically establish money laundering. The relevant statutory requirements, including knowledge and intentional conduct, must be assessed against the available evidence.
The Criminal Consequences
The penalties under the 2025 law are significant. Article 26 provides for imprisonment of between one and ten years and a fine of Dh100,000 to Dh5 million, or an amount equivalent to the value of the criminal property, whichever is greater.
The legislation also prescribes enhanced punishment where specified aggravated circumstances are established. These include exploiting influence or authority arising from a person's position or professional activity, committing the offence through a non-profit organisation or an organised criminal group, certain specified predicate offences and repeat offending. The penalty is temporary imprisonment and a fine of between Dh1 million and Dh10 million, or twice the value of the relevant criminal property, whichever is greater.
The consequences may extend beyond imprisonment and fines. Competent authorities may take measures to identify, seize or freeze suspected criminal assets, while confiscation may be ordered in accordance with the law.
For someone who agreed to process payments in return for a relatively small commission, the financial and criminal consequences can be disproportionate to the amount received.
When Cybercrime Offences are Also Involved
Money mule operations frequently rely on digital platforms and electronic transactions. Criminal networks may use false identities, fabricated company profiles, forged documents and payment instruments to facilitate the movement of funds.
Federal Decree-Law No. 34 of 2021 on Countering Rumours and Cybercrimes contains provisions that may apply to aspects of these activities. Article 11 addresses the creation of fake websites, electronic accounts and email addresses falsely attributed to another natural or legal person.
Article 14 deals with the forgery of electronic documents and the knowing use of forged documents. Article 15 covers the forgery, cloning or copying of credit cards, debit cards and other electronic payment instruments, as well as the capture of their data or information.
These provisions may become relevant where criminal networks impersonate individuals or companies, create fictitious online business profiles, use forged electronic invoices or forge payment instruments. Depending on the conduct and the evidence, a scheme may give rise to investigations involving both money laundering and cybercrime offences.
When an Individual Claims to Have Been Deceived
One of the important questions in a money mule investigation is whether the account holder knew, or had sufficient indications or evidence to believe, that the funds were connected to criminal activity.
Consider an individual who responds to an online advertisement for a remote administrative position. The supposed employer explains that the job involves receiving customer payments into a personal bank account and transferring them to other accounts. In return, the individual is offered a monthly salary and an additional commission for each transaction.
The arrangement may initially appear genuine. However, the person is subsequently instructed to accept transfers from unrelated individuals, forward the money immediately, retain a percentage and avoid contacting the senders. If the funds are later traced to fraudulent activity, the account holder's role may come under scrutiny.
Investigators may examine the nature of the employment offer, the value and frequency of transfers, the commission received and communications with the supposed employer. Instructions to conceal transactions from the bank, share banking credentials or provide misleading explanations may also be relevant.
A person who has genuinely been deceived should not automatically be treated as a money launderer. Equally, a claim that the account holder did not know where the money came from will not, by itself, resolve the matter. The individual's conduct and the surrounding evidence will be important in determining whether the legal requirements for an offence have been satisfied.
The Risks of Using Companies and False Invoices
Criminal networks may use registered businesses to give illicit funds the appearance of legitimate commercial income. Corporate accounts can be used to receive payments supported by invoices for consultancy, marketing, equipment or other services that were never supplied.
Once the money enters the business account, it may be transferred to other entities, withdrawn or converted into virtual assets. The use of commercial documents can make the transactions appear routine, even when there is no genuine business purpose behind them.
Company registration and possession of a trade licence do not legitimise criminal proceeds. Directors, managers and business owners should ensure that payments correspond to actual supplies or services and that invoices are supported by appropriate contracts and records.
Unexplained transfers from unrelated third parties, unusually high commissions and requests to process payments outside the company's normal activities should be examined carefully. Businesses should also be alert to attempts to use their accounts as a channel for funds unrelated to their operations.
Steps to Protect Personal and Corporate Accounts
Individuals should not rent out their bank accounts, hand over debit cards or share passwords, PINs, one-time passwords or online banking access with third parties. Offers of employment that require a person to receive money into a personal account and transfer it elsewhere should be treated with particular caution.
Anyone approached with such a request should retain relevant messages, emails and other communications. If suspicious funds have already been received or transferred, the individual should contact the bank through its official channels and obtain appropriate legal advice. Further transfers should be avoided, and relevant records should not be deleted or altered.
Businesses need controls that verify customers, suppliers and other counterparties, establish the commercial purpose of payments and restrict access to corporate banking facilities. Accounting records, contracts and invoices should accurately reflect genuine transactions. Unexplained payments should be referred to the appropriate compliance personnel.
Financial institutions, designated non-financial businesses and professions (DNFBPs), virtual asset service providers and other regulated entities may also be subject to obligations under the UAE's anti-money laundering framework. These can include customer due diligence, transaction monitoring, record-keeping and suspicious transaction reporting.
The Role of Investigations and International Cooperation
Suspicious financial activity can trigger reporting and other measures under the applicable legal framework. Depending on the circumstances and legal authority, transactions may be suspended and funds frozen while competent authorities examine the activity.
Investigations may follow the movement of money across multiple bank accounts, companies and digital wallets. Banking records, electronic communications, transaction histories and commercial documents can help establish who controlled the funds, how they were transferred and whether the accounts were used to conceal criminal proceeds.
Cross-border cooperation is also important. Funds may pass through several jurisdictions before reaching their intended beneficiaries, making it necessary for UAE authorities to work with foreign counterparts and financial institutions to trace transactions and identify those involved.
Conclusion: The Cost of Handling Money for Others
Money mule arrangements demonstrate how easily personal bank accounts, corporate banking facilities and digital wallets can be exploited by criminal networks. What appears to be a convenient source of additional income may expose an individual to investigation, imprisonment and substantial financial penalties.
The UAE's anti-money laundering and cybercrime laws provide a framework for investigating the movement and concealment of criminal proceeds. At the same time, genuine victims of deception must be distinguished from individuals who knowingly participate in such arrangements. The circumstances of each case, particularly what the account holder knew and how they acted, remain critical.
For residents and businesses, the safest course is to reject unexplained payment requests, protect banking credentials and ensure that every transaction has a genuine and verifiable purpose. Allowing another person to use an account is not simply a banking decision; depending on the circumstances, it can carry serious legal consequences.
Dubai Civil Court Orders Man to Repay Dh266,000 in Failed Investment Deal
Investor awarded Dh50,000 in compensation after court finds only part of the money entrusted for vehicle purchases was returned.
Dubai Civil Court has ordered a man to repay approximately Dh266,000 to an investor after finding that he had failed to return money entrusted to him for investment in various projects and vehicle purchase deals. The court also awarded the claimant Dh50,000 in compensation for material and moral damages, together with annual interest of 5 per cent until full payment.
The case dates back to July 2023, when the defendant allegedly persuaded the plaintiff to invest money in projects promising substantial returns. He later sought additional funds to participate in vehicle purchase transactions, claiming that the money was required to meet administrative expenses and customs duties.
Acting on these assurances, the plaintiff transferred money through bank transactions, arranged an additional transfer through a friend and handed over further sums in cash, as requested by the defendant.
According to a report prepared by a financial expert appointed by the court, the total amount established as having been transferred or handed over to the defendant was approximately Dh366,000.
The amount included bank transfers and cash delivered to the defendant's driver, as supported by WhatsApp correspondence between the parties. The expert's findings also established that the defendant had repaid only Dh100,000, leaving approximately Dh266,000 outstanding.
During the proceedings, the defendant disputed the outstanding liability, claiming that he had returned additional amounts in cash. He relied on the testimony of two witnesses to support his defence. However, the court found their statements insufficient to establish that the remaining debt had been settled, particularly in the absence of documentary evidence confirming the alleged repayments.
After reviewing the bank records, electronic communications and financial expert's report, the court held that the responsibility to prove that an outstanding debt had been discharged rested with the party asserting that repayment had been made.
Since the defendant had failed to produce sufficient evidence showing that the remaining amount had been returned, the court concluded that the plaintiff was entitled to recover the unpaid balance of approximately Dh266,000.
The court also held that the failure to return the money had deprived the plaintiff of the opportunity to use his funds, resulting in both financial loss and moral harm. Taking these circumstances into account, it awarded Dh50,000 in compensation.
In its final ruling, the court ordered the defendant to pay approximately Dh266,000, together with Dh50,000 in compensation and annual interest at 5 per cent from the date the legal claim was filed until full settlement. The defendant was also directed to bear the court charges, legal expenses and lawyer's fees.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
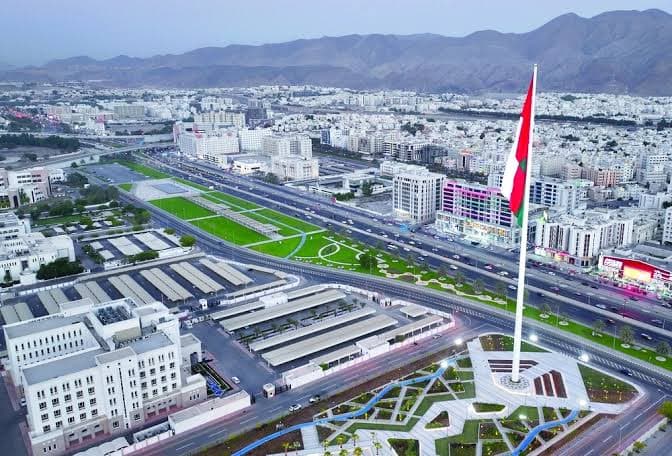
Oman Sultan Issues Four Decrees Establishing Legal Framework For Global Financial Centre
New laws cover the centre’s operations, regulatory oversight, courts and complementary tax obligations for multinational groups.
His Majesty Sultan Haitham bin Tarik has issued four Royal Decrees establishing the legal and regulatory framework for the International Financial Centre of Oman.
Royal Decree No. 102/2026 promulgates the Operating Law of the International Financial Centre of Oman, while Royal Decree No. 103/2026 introduces its Regulatory Law. Royal Decree No. 104/2026 promulgates the Courts Law governing the centre, and Royal Decree No. 105/2026 introduces the Complementary Tax Law for entities of multinational groups operating within the centre.
Under the four decrees, the respective laws attached to each decree will come into force. The provisions of the Operating Law, Regulatory Law and Courts Law will be enforced in accordance with Articles 1 of Royal Decrees Nos. 102/2026, 103/2026 and 104/2026.
Royal Decree No. 105/2026 provides for the enforcement of the Complementary Tax Law for the Entities of Multinational Groups of the International Financial Centre of Oman, issued under Royal Decree No. 70/2024.
All four decrees stipulate that they must be published in the Official Gazette and will enter into force on the day following their respective dates of publication.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
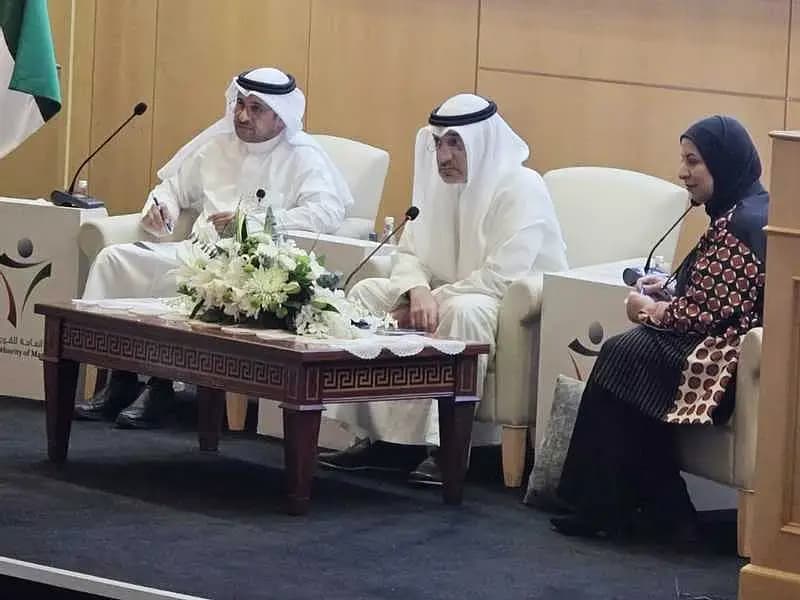
Kuwait Cabinet Approves GCC Excise Tax Framework, Paving Way For New Levies
Proposed legislation seeks to align Kuwait with GCC’s taxation system, with excise duties of up to 100 per cent.
Kuwait’s Cabinet on Tuesday approved a draft decree-law concerning the Unified Excise Tax Agreement among Gulf Cooperation Council (GCC) member states and its amending annex, referring the measure to HH the Amir Sheikh Meshal Al-Ahmad Al-Jaber Al-Sabah for approval.
The move marks an important step towards introducing a unified excise taxation framework in Kuwait, bringing the country closer to the indirect tax system already adopted by other GCC members. The agreement provides for levies on specific products considered harmful to human health or the environment, as well as certain luxury goods. The framework is intended both to discourage consumption of such products and to strengthen government revenues beyond dependence on oil.
Under the proposed arrangement for Kuwait, the main categories expected to attract excise tax include tobacco and its derivatives, energy drinks, carbonated beverages and other sweetened drinks. The anticipated rates are 100 per cent for tobacco products and energy drinks, while carbonated drinks are expected to attract a 50 per cent levy. Taxation of other sweetened beverages is expected to vary according to their sugar content.
The amending annex to the GCC agreement also provides greater flexibility in determining how excise tax is calculated. Rather than relying exclusively on a percentage of a product's value, the revised framework allows the tax to be imposed as a fixed amount for each unit, based on its quantity, or through a combination of value-based and quantity-based calculations.
It also revises the basis for determining the taxable value, providing for the retail selling price specified by the producer or importer, or the applicable standard price agreed between tax authorities of member states, whichever is higher. The tax and value-added tax are excluded from this calculation. The ministerial committee responsible for the agreement will also have the authority to revise the list of taxable products.
For businesses involved in importing, manufacturing and distributing the affected products, the introduction of the framework is expected to bring additional tax and compliance responsibilities. Product classification, pricing, inventory management and tax reporting will become important considerations once the implementing provisions are finalised.
The Cabinet's approval is a legislative step towards adopting the agreement in Kuwait. However, the tax will not take effect merely through the approval of the draft decree-law. Its implementation will depend on the completion of the required legal procedures, formal issuance and publication of the relevant legislation, together with further guidance on the effective date and administrative requirements.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
UAE Businesses Face E-Invoicing Deadlines As FTA Warns Of Dh5,000 Monthly Penalties For Non-Compliance
Businesses must meet phased implementation deadlines as the UAE moves towards a fully digital invoicing framework.
The UAE Federal Tax Authority (FTA) has urged businesses and other entities covered by the country's e-Invoicing System to meet the prescribed implementation deadlines, warning that delays could attract administrative penalties of Dh5,000 for each month or part of a month of non-compliance.
Businesses and other entities with annual revenues of Dh50 million or more were required to appoint an Accredited Service Provider (ASP) by October 30, 2026, and must implement the e-Invoicing System by January 1, 2027.
The FTA said early preparation was essential to ensure a smooth transition and avoid penalties. It encouraged affected businesses to begin the necessary procedures well before the deadlines, including selecting a suitable accredited service provider, entering into an agreement and completing the required technical integration.
Entities must also follow the prescribed procedures through EmaraTax, the FTA's digital tax services platform, as part of the process of joining and activating the system.
For businesses and other persons with annual revenues below Dh50 million, the deadlines are later. They must appoint an Accredited Service Provider by March 31, 2027, and implement the e-Invoicing System no later than July 1, 2027.
Under the applicable legislation, a penalty of Dh5,000 applies for every month or part of a month of delay in implementing the system. The same penalty applies where an entity fails to appoint an accredited service provider within the prescribed timeframe. The measure is intended to encourage timely compliance as the UAE advances its digital transformation of tax administration and business processes.
The FTA said the system had undergone testing during a pilot phase ahead of mandatory implementation. The exercise assessed the effectiveness of technical integration, the user experience and the preparedness of the participating parties to meet the system's operational requirements.
The authority has also adopted a phased approach and maintained communication with stakeholders in both the public and private sectors to help ensure that businesses are ready before their respective implementation deadlines.
To facilitate the transition, the FTA said it had introduced flexible implementation arrangements and simplified procedures aimed at minimising disruption to business operations while supporting compliance with the regulatory framework.
As part of its awareness programme, the authority has been conducting in-person events across the UAE alongside virtual information sessions. These initiatives are designed to explain which businesses and entities fall within the scope of the system, the applicable implementation requirements, the process of connecting to the platform and the steps required for activation through EmaraTax.
In September 2026, the FTA organised an expanded joint meeting in Dubai, bringing together accredited e-Invoicing service providers, businesses and other entities covered by the system, as well as authority officials and specialists.
The meeting gave participants an opportunity to engage with accredited service providers and assess which would be suitable for their operational requirements. It also provided guidance on the legal and regulatory framework, the procedures for joining the system and the practical steps involved in implementation.
The gathering was intended to strengthen coordination between businesses and service providers and support an orderly transition to the new digital invoicing framework. The FTA described e-invoicing as an important development in improving compliance through secure, efficient and standardised digital processes.
The authority has called on all persons subject to the system to familiarise themselves with the relevant legislation, requirements, procedures and guidance well ahead of their respective deadlines. Further information and implementation guidance are available on the FTA's official website under its e-Invoicing section.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Dubai Court Declares Man Insolvent Over Dh1.029 Million Debt To Three Banks
Loan installments exceeded debtor’s monthly salary, while a probe found no assets available for liquidation
Dubai Civil Court has declared a Gulf national insolvent after finding that he owed three banks a total of Dh1.029 million but had no assets available to repay the debts.
The court ordered the termination of the insolvency proceedings and barred the man from obtaining new loans or financing for three years, in accordance with the legal provisions governing insolvency.
The decision followed a report by the insolvency trustee, which found that the debtor had no funds or properties that could be liquidated to settle his outstanding liabilities.
The debtor had obtained bank financing worth Dh550,000 in November 2024, with monthly instalments of Dh13,000. After he stopped making payments, the financing bank presented a cheque for Dh550,000 in September 2025, but it was returned because of insufficient funds. The bank’s claim subsequently reached Dh555,000.
In May 2025, the man also secured a personal loan of Dh395,000 from another bank, requiring monthly instalments of Dh9,257. He had additionally accumulated credit card debts with two other banks, with the outstanding balance on one card reaching Dh80,000. The total debt recognised by the court amounted to Dh1,028,980.
Court documents showed that the debtor held a government job and earned a gross monthly salary of Dh20,645. However, the combined monthly installments on his two loans alone totalled Dh22,257, exceeding his salary before accounting for credit card payments and everyday living expenses.
The debtor told the court that he spent approximately Dh21,000 a month supporting his family. The documents also established that he owned no property registered in his name, held no trade licences and had no shares listed on the Dubai Financial Market. He lived with his family in a property owned by another person.
An examination of his bank accounts revealed only limited balances. His sole identified vehicle was a 2011-model car, which the court considered necessary for his personal use and daily living.
The insolvency trustee concluded that there were no assets available for liquidation and that the balances in the debtor’s bank accounts did not exceed what was required to meet his basic needs. The court consequently found that further liquidation proceedings would serve no purpose and declared him insolvent before terminating the case.
The debtor’s legal representative, said insolvency decisions involving financially distressed individuals were based on a comprehensive assessment of their financial circumstances, including their debts, bank balances and available assets.
Such proceedings often establish that a debtor cannot meet financial obligations and has no assets that can be liquidated to repay creditors, he said.
Declaring an individual insolvent is a judicial process intended to regulate the debtor’s legal position under the applicable rules. The resulting statutory restrictions remain in force for three years, while the individual’s basic needs and family responsibilities are taken into consideration, he added.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Abu Dhabi Civil Court Orders Compensation Over Telegram Investment Fraud
Victim to receive Dh59,153 in recovered funds and Dh3,500 in damages after defendants were convicted of fraud.
The Abu Dhabi Family, Civil and Administrative Cases Court has ordered several individuals to repay Dh59,153 obtained through a fake trading and investment scheme promoted on Telegram, along with Dh3,500 in compensation for financial and emotional harm.
The victim was persuaded to transfer money to the defendants’ bank accounts in three installments after being offered what was presented as a trading and investment opportunity. The defendants subsequently refused to return the funds.
A criminal court had previously convicted the defendants of fraud and ordered their deportation instead of imprisonment. The judgment also held them responsible for the costs of the criminal proceedings.
In the subsequent civil case, the complainant sought repayment of the misappropriated amount and Dh200,000 in compensation for material and emotional damages. He also claimed Dh2,000 towards criminal proceedings costs, annual legal interest of 12% from the date of the criminal judgment until full payment, and court fees and expenses.
The complainant submitted the criminal judgment, related notifications, invoices, payment receipts and a certificate confirming that no appeal had been filed.
The civil court found that the final criminal judgment had established the defendants’ responsibility for fraudulently obtaining Dh59,153 from the complainant. As there was no evidence that the money had been returned, the court ordered the defendants to repay the full amount.
The court also recognised the financial burden caused by the defendants’ conduct, including the need to take legal action to recover the money. It awarded Dh2,300 for financial loss and a further Dh1,200 for non-financial harm, including emotional distress, anxiety and loss of peace of mind. The total compensation was set at Dh3,500, in addition to repayment of the original Dh59,153.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
UAE Bank Ordered To Refund Dh92,854 Over Unproven Credit Card Charges
The court found that the bank had failed to prove the customer agreed to the interest and fees charged on his credit card.
An Abu Dhabi court has ordered a bank to refund Dh92,854 to a customer, close his credit card account and confirm that he has no outstanding liability after the lender failed to provide documentary evidence supporting the interest and fees it had charged.
The court also ordered the bank to pay annual interest of 3 per cent on the refund from the date the lawsuit was filed until payment, subject to a cap equal to the principal amount.
The customer told the court that he had applied for financing from the bank in 2013 and received a credit card with a Dh50,000 limit. He maintained that he had settled all his dues, including payments exceeding the amount owed, but the bank continued to demand further sums.
A court-appointed banking expert examined the account statements and found that the bank could not produce the original credit card application or documents establishing the interest rate and fees agreed with the customer. The bank attributed the absence of these records to a fire at the premises where its documents were stored.
The expert recalculated the account using simple legal interest, excluding compound interest and charges that the bank could not demonstrate had been agreed. The review showed that the customer had made withdrawals totalling Dh1.403 million and payments of Dh1.605 million. After adjusting the account, the expert concluded that the bank owed him Dh92,854.
Court Accepts Expert's Findings
The court accepted the expert's conclusions, finding that the assessment was based on the account statements and supported by adequate technical reasoning. It noted that the expert had addressed the bank's objections and that the lender had produced no evidence sufficient to undermine the report.
The court also found that the bank had repeatedly delayed payment despite the amount being due to the customer. It ordered the lender to refund Dh92,854, pay the stipulated interest, clear all outstanding credit card liabilities, close the account and issue a certificate confirming that the customer had no remaining debt.
The bank was further directed to bear the court costs and pay Dh200 in legal fees. The court dismissed the customer's remaining claims.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Court Acquits Woman of Embezzlement Over Doubts About WhatsApp Evidence
Judges overturn conviction, citing inconsistent testimony and lack of reliable proof that money was entrusted to the accused.
An Ajman appeal court has acquitted an Egyptian woman of embezzlement, overturning her earlier conviction after finding inconsistencies in the complainant’s account and insufficient evidence to establish that she had received the money in question.
The woman, a retired dentist who is now a homemaker, was convicted by a court of first instance in July and fined Dh5,000, in addition to court fees. She denied knowing the complainant, receiving any money from him or participating in the WhatsApp conversations attributed to her.
The complainant alleged that the woman had received money under an agency arrangement but subsequently misappropriated it. However, the appeal court found that his statements about how the money had been handed over and the amount allegedly paid were unclear and inconsistent.
The defence also challenged the authenticity of WhatsApp screenshots submitted as evidence. It pointed out that the telephone number displayed in the images began with ‘05’ but did not include the UAE’s international dialling code, +971. This raised questions about whether the screenshots accurately represented the original conversations.
The defence argued that the images could have been altered using photo-editing software and questioned whether they were coloured copies rather than original electronic records. It also maintained that the screenshots could not reliably establish who had created or sent the messages.
No forensic report was presented to verify that the conversations originated from the woman’s telephone or WhatsApp account. She had consistently denied the allegations, including any knowledge of the number associated with the messages, from the time she was questioned by police.
The court’s concerns extended beyond the digital evidence. It found no reliable documents or supporting witness testimony to substantiate the complainant’s version of events. The case papers also contained no independent police inquiries confirming the circumstances of the alleged transaction or establishing the authenticity of the accusation.
The judges questioned why the complainant would have entrusted a substantial sum to the woman when the available evidence disclosed no established relationship between them. They also noted the absence of material showing that the complainant was engaged in commercial activities or that the two parties had entered into a documented business transaction.
The first-instance court had concluded that the allegation was supported by the complainant’s account, the woman’s purported confession and other circumstantial evidence. On appeal, however, the defence disputed the claim that she had confessed, arguing that the case file contained no such admission. It also maintained that she had not been questioned by prosecutors and had consistently denied the accusation in her police statement and before the trial court.
The woman was charged with breach of trust under Article 453 of the UAE Crimes and Penalties Law. Her defence argued that establishing the offence required proof that the money had first been entrusted to her through a recognised relationship of trust, such as an agency arrangement.
Without reliable evidence that the complainant had handed over the money, the defence maintained, it could not be established that the funds had entered the woman’s custody or that she had subsequently dealt with them as her own.
The appeal court reiterated that criminal convictions must rest on certainty rather than suspicion or speculation. Where the evidence is unreliable or insufficient to establish guilt, the accused must be acquitted.
The three-judge panel unanimously ruled that the evidence did not justify upholding the conviction. It overturned the first-instance judgment and declared the woman not guilty.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Abu Dhabi Court Orders Man To Repay Dh180,266 Loan Admitted On WhatsApp
WhatsApp messages and emails helped establish the outstanding debt after the borrower repaid only Dhs12,000.
The Abu Dhabi Family, Civil and Administrative Cases Court has ordered a man to repay Dhs180,266 to another individual after WhatsApp messages and emails established his acknowledgement of the debt.
The dispute arose from a relationship of trust between the two parties. The defendant had approached the plaintiff for financial assistance, prompting the latter to secure a loan from a financing institution and transfer the funds to him.
According to the case details, the plaintiff obtained Dhs160,000 through the financing facility and transferred the amount to the defendant. The parties subsequently agreed that the defendant would cover the full financing obligation, bringing the total debt to Dhs192,266.
The plaintiff told the court that the agreement, including the repayment arrangement, had been acknowledged through emails and WhatsApp conversations. He also claimed that the defendant had offered a distinctive vehicle registration number as security but later sold the vehicle and retained the proceeds without settling the outstanding debt.
The defendant had repaid only Dhs12,000, leaving Dhs180,266 unpaid.
The plaintiff approached the court to recover the outstanding balance, while reserving his right to pursue additional claims for damages, court fees, expenses and legal costs.
In its ruling, the court relied on the correspondence exchanged between the parties, which included clear acknowledgements of the debt and confirmation that the defendant had received Dhs160,000.
The court concluded that the evidence established the loan transaction and the total amount payable at Dhs192,266. After deducting the Dhs12,000 already repaid, it ordered the defendant to pay the remaining Dhs180,266.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.